
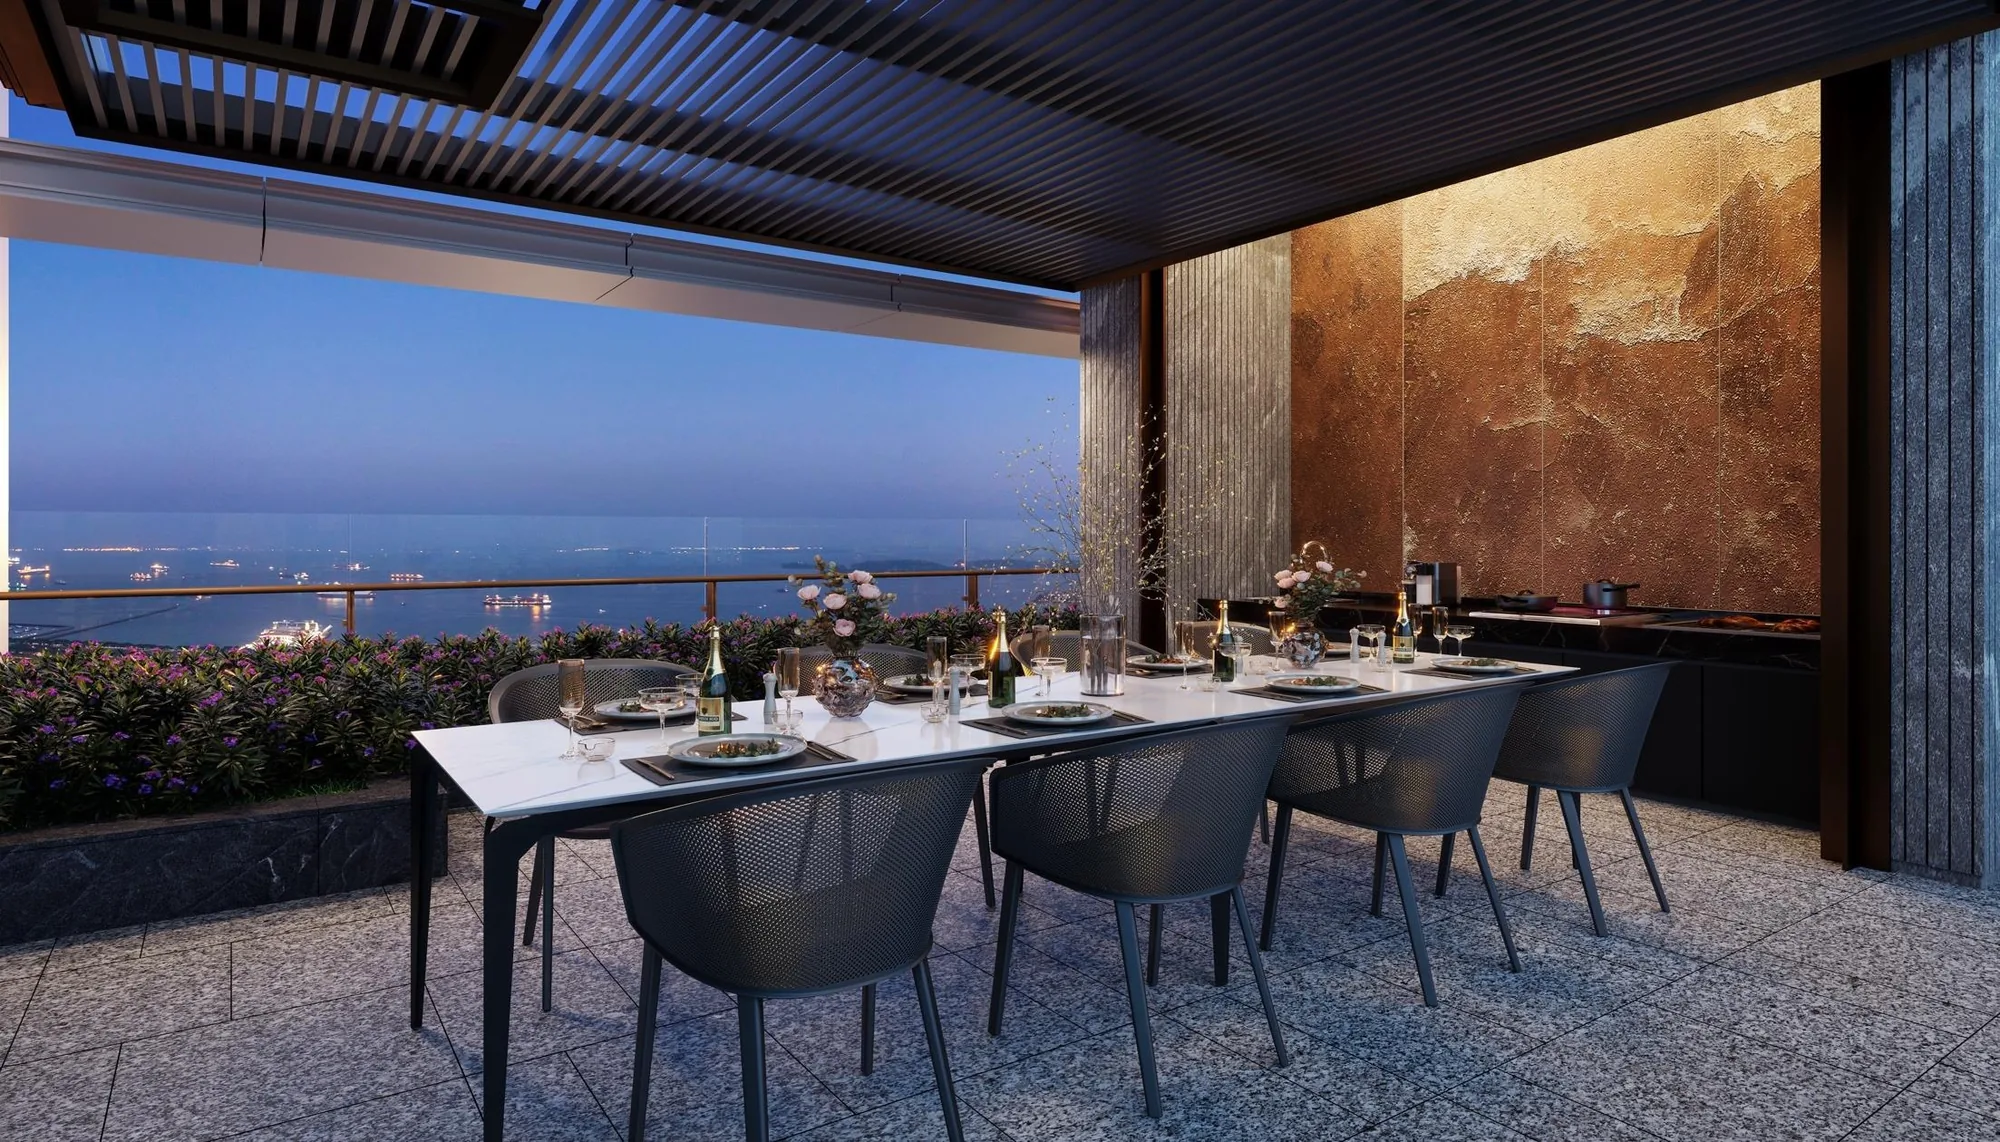
 Artist’s impression
How much a bank may lend on a home at W Residences Marina View is set by two MAS rules: the loan-to-value (LTV) limit, which is measured against the price, and the Total Debt Servicing Ratio (TDSR), which is measured against income. The figures below were in force on 20 October 2026.
W Residences Marina View Loan-to-Value Limits
The limit depends on how many housing loans the borrower already has outstanding. Each tier has a standard limit, a lower limit and a minimum share of the price to be paid in cash.
| Outstanding housing loans | Standard LTV | Lower LTV | Minimum cash |
|---|---|---|---|
| None | 75% | 55% | 5% (10% in the lower band) |
| One | 45% | 25% | 25% |
| Two or more | 35% | 15% | 25% |
Source: MAS, checked 20 October 2026. Limits can change; confirm with MAS or your bank before signing.
The Lower LTV Band at W Residences Marina View
A loan moves into the lower band if either of these is true:
- its tenure is longer than 30 years; or
- it would run past the borrower’s 65th birthday, taking the income-weighted average age when two people borrow together.
So a buyer of 33 taking a 35-year loan is caught twice, by the tenure and by finishing at 68, while a buyer of 42 on a 25-year loan stays within 30 years but finishes at 67 and is caught by the age test alone. Loans for private homes can run for up to 35 years.
Over 30 years, or beyond 65.
The limit falls to 55%, 25% or 15%, and the cash minimum on a first loan doubles to 10%.
W Residences Marina View Buyers and the TDSR
All monthly debt repayments, including the new home loan, must stay within 55% of gross monthly income. Banks test the new loan at a medium-term interest rate rather than the rate on offer, so that it would still be affordable if rates rose.
| Rule | As at October 2026 |
|---|---|
| TDSR limit | 55% of gross monthly income |
| Interest rate used for the test | 4%, or the loan’s own rate if higher |
| Variable and rental income | Counted at 70%, after a 30% haircut |
| Longest tenure, private property | 35 years |
| Joint borrowers | Income-weighted average age |
Source: MAS, checked 20 October 2026. Limits can change; confirm with MAS or your bank before signing.
Fixed salary is counted in full. Existing car loans, other property loans and minimum card payments are deducted first, and the balance of the 55% is turned into a loan amount. The W Residences Marina View TDSR calculator applies these rules for one or two borrowers.
W Residences Marina View: In-Principle Approval First
Many buyers ask a bank for an in-principle approval before choosing a home. It states how much the bank expects to lend on the information given, subject to final approval and valuation, and turns the stamp duty, the booking fee and the cash share into firm figures. Each bank sets its own terms and how long the approval lasts.
After the buyer’s own share is paid, the loan is drawn stage by stage under the payment scheme; the progressive payment calculator shows the split at each stage.
Request the W Residences Marina View Price List
W Residences Marina View is on sale, and the Sales Concierge sends the current price list with the homes still available in the tower. Showflat viewings are arranged by appointment through the Sales Concierge.
Sent on request
- The current price list with the homes still available.
- The e-brochure and the floor plans for the home types you shortlist.
- A worked payment schedule and the stamp duty for your profile.
- A showflat appointment arranged around your diary.
Request the Price List
No obligation. The Sales Concierge responds personally to every enquiry.
Prefer to speak to someone? Call +65 6200 6220, or send a WhatsApp message to the same number.